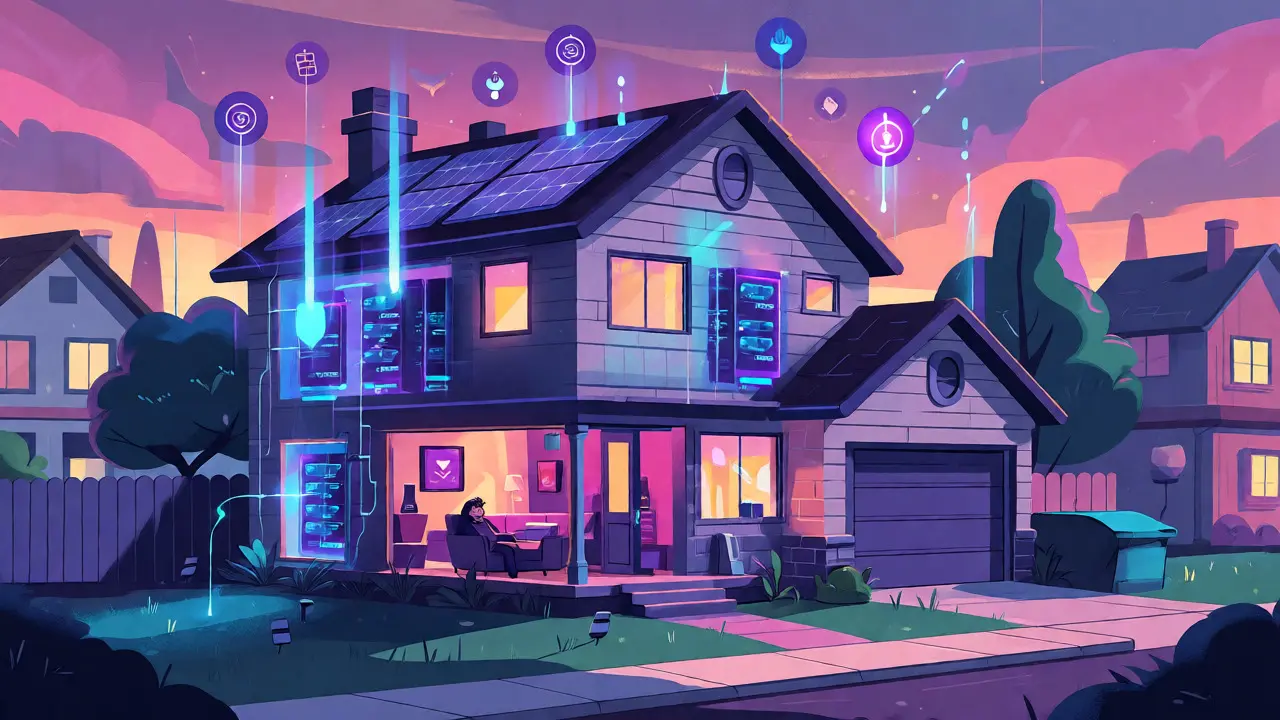

Imagine you have a house. You live in it, pay the mortgage, and keep it secure. Now imagine you can rent out the basement, the garage, and even the roof for storage or solar panels-all while still living there. That’s essentially Restaking in cryptocurrency. It allows you to use your existing stake to secure multiple networks at once, earning more rewards without needing extra capital.
This isn't just a theoretical idea. Since EigenLayer launched its mainnet in March 2024, over $20 billion has been locked into restaking protocols. If you're an Ethereum validator or a holder of liquid staking tokens, understanding this mechanism is no longer optional-it's key to maximizing your yield in a maturing market.
The Core Problem: Why Restaking Exists
To get why restaking matters, you have to look at how blockchain security works. Most new blockchains need their own validators to stay safe. Bootstrapping that security from scratch is hard and expensive. They either have to attract thousands of independent validators or rely on a small group with high trust assumptions.
Restaking solves this by letting Ethereum's massive pool of staked ETH (over 15% of all staked value as of late 2024) extend its security to other services. These services are called Actively Validated Services, or AVSs. Think of AVSs as anything that needs verification but doesn't necessarily need its own dedicated blockchain-like oracle networks, data availability layers, or bridge operators.
Before restaking, if you wanted to secure an oracle network, you had to run a separate node and stake separate collateral. With restaking, you use your existing Ethereum stake as collateral for both Ethereum and the oracle network simultaneously. This creates what Sreeram Kannan, the founder of EigenLayer, calls an "internet bond market." Capital becomes incredibly efficient because one dollar of stake secures multiple assets.
How It Actually Works: Native vs. Liquid Restaking
There are two main ways to participate in restaking, and they suit different types of users. Choosing the right one depends on your technical skills and how much control you want.
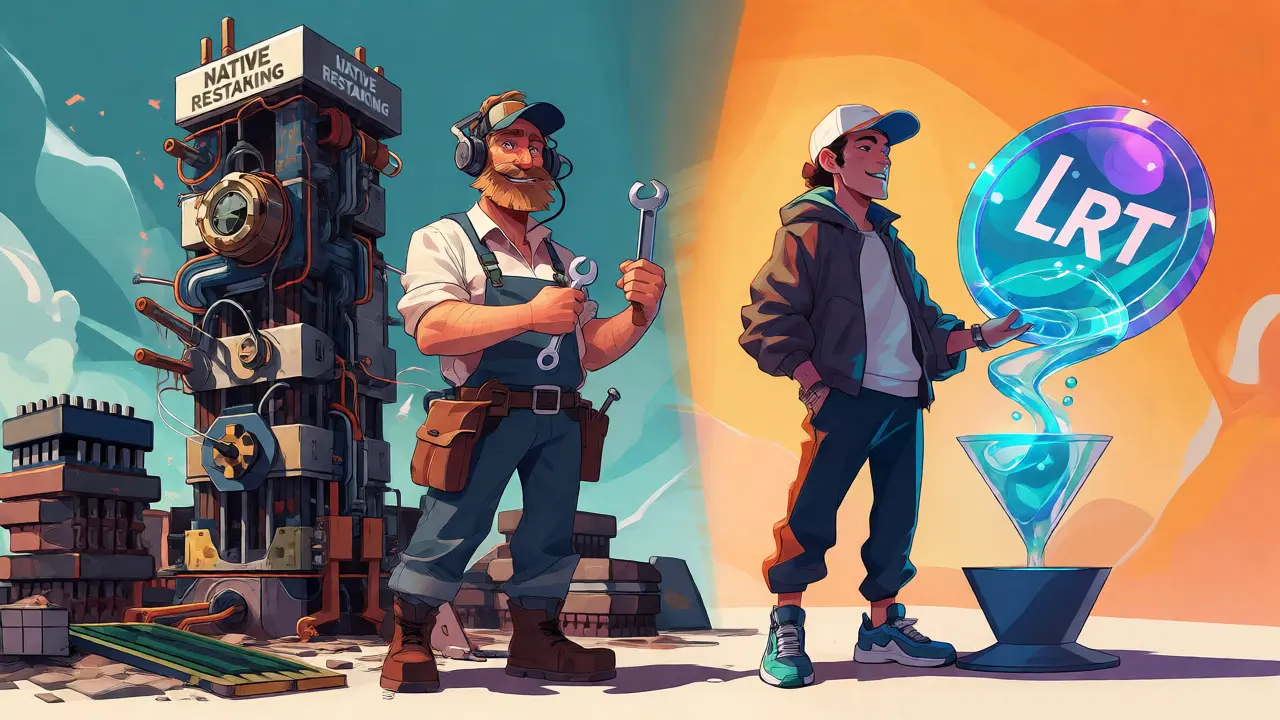
Native Restaking is for power users who run their own validator nodes. You need the full 32 ETH minimum for an Ethereum validator. To restake natively, you install additional software modules provided by protocols like EigenLayer. Your withdrawal credentials are modified so that EigenLayer smart contracts hold rights to your stake. This gives you maximum control but requires serious hardware (8+ CPU cores, 16GB RAM) and constant monitoring.
Liquid Restaking is where most retail investors land. Instead of running a node, you stake ETH with a provider like Lido or Rocket Pool, receiving a Liquid Staking Token (LST) like stETH. Then, you deposit that LST into a restaking protocol. In return, you get a Liquid Restaking Token (LRT), such as eETH from Ether.fi. These LRTs are tradable and often automatically accumulate rewards from both the base layer and the AVSs.
| Feature | Native Restaking | Liquid Restaking |
|---|---|---|
| Minimum Requirement | 32 ETH + Node Hardware | Any amount (via LSTs) |
| Technical Skill | High (DevOps required) | Low (DeFi interaction) |
| Control | Full control over keys/slashing | Custodial risk with providers |
| Yield Potential | Higher (no operator fees) | Slightly lower (fees deducted) |
| Liquidity | Locked until unstaking period | High (tradeable LRTs) |
The Role of EigenLayer and AVSs
You can't talk about restaking without talking about EigenLayer. Developed by Sreeram Kannan, a professor at the University of Washington, EigenLayer pioneered the concept. It acts as the middleware connecting Ethereum validators to various AVSs.
Here’s the flow: An AVS developer wants security for their service. They register on EigenLayer and define their slashing conditions (rules for penalties). Validators then opt-in to secure that specific AVS. If a validator fails to perform their duty for that AVS-say, failing to report data correctly for an oracle-they get slashed. The penalty comes directly from their staked ETH.
This creates a free-market dynamic. AVSs compete for validators by offering higher yields. Validators compete for AVSs by offering better reliability. As of October 2024, EigenLayer controls roughly 89% of the restaking market share, though competitors like Renzo Protocol and EtherFi are growing fast.
Risks: The Double-Edged Sword
Higher yield always comes with higher risk, and restaking introduces complex new vectors. While standard Ethereum staking might yield 3-5% APY, restaking can push total returns to 8-12%. But that extra reward is compensation for added danger.
The biggest risk is Slashing. In native staking, you only face Ethereum's slashing rules. In restaking, you face slashing conditions from every single AVS you support. Trail of Bits, a prominent security firm, warns about the "combinatorial explosion" of these conditions. If you restake across ten different AVSs, you have ten different sets of rules that could trigger a penalty. A minor connectivity issue on one node could theoretically lead to losses across multiple protocols.
Another concern is systemic risk. Vitalik Buterin has expressed cautious support but warned that concentrating security across many protocols through a single layer could amplify incidents. If a major bug hits EigenLayer itself, it could impact billions of dollars in staked ETH. Furthermore, liquid restaking adds another layer of dependency. If the LST provider fails, or if the LRT loses its peg during a market crash, your position could suffer cascading effects.
Who Should Consider Restaking?
Not everyone needs to jump in immediately. Here is a quick heuristic to decide:
- Go for it if: You already hold liquid staking tokens (like stETH or rETH), you understand DeFi risks, and you are comfortable with slightly lower liquidity in exchange for higher yield.
- Wait if: You are new to crypto, you don't understand slashing, or you need immediate access to your funds without any lock-up periods.
- Run your own node if: You have 32+ ETH, technical DevOps skills, and want to avoid paying the 5-10% operator fees common in delegated models.
Data shows that about 65% of EigenLayer users choose to delegate to professional operators rather than running their own infrastructure. This suggests that for most people, the convenience of liquid restaking or delegated native restaking outweighs the marginal gain of self-custodying the validation process.
The Future Outlook
The restaking landscape is evolving rapidly. Analysts from Blockworks Research predict the Total Value Locked (TVL) could hit $100 billion by 2026. We are seeing increased integration between restaking and traditional finance concepts, with some calling it the "bond market of the internet."
However, regulatory clouds remain. The U.S. SEC has hinted that certain restaking arrangements might be viewed as securities offerings. Compliance will likely become stricter as the market matures. Additionally, we expect more sophisticated risk assessment tools. EigenLayer has already introduced caps on how much security a single AVS can claim, addressing concerns about concentration risk.
For now, restaking represents one of the most significant innovations in proof-of-stake mechanics since the Merge. It turns idle capital into active security infrastructure. Just remember: the complexity is real. Do not allocate money you cannot afford to monitor closely.
Is restaking safer than regular staking?
No, it is generally considered riskier. While the underlying asset (ETH) remains the same, restaking exposes you to additional slashing conditions from third-party AVSs. Regular staking only subjects you to Ethereum's native consensus rules.
Do I need 32 ETH to start restaking?
Only if you are doing native restaking with your own validator. If you use liquid restaking via tokens like stETH or eETH, you can start with any amount, similar to buying a stock fraction.
What happens if an AVS gets hacked?
If the hack results in a violation of the AVS's slashing conditions, validators securing that AVS may be penalized. The extent of the loss depends on the specific terms defined by the AVS developer when they registered on the restaking protocol.
Can I withdraw my funds anytime?
With liquid restaking tokens (LRTs), you can usually trade them on secondary markets instantly. However, redeeming them for the underlying ETH involves a queue system managed by the staking provider, which can take days depending on network congestion.
Which platforms dominate restaking?
EigenLayer is the primary protocol for native restaking. For liquid restaking, popular options include Ether.fi, Renzo Protocol, and Puffer Finance, which offer user-friendly interfaces and liquid tokens representing restaked positions.
Comments (5)

- Richard Moore
- September 29, 2026 AT 22:27 PM
Yo this is actually super helpful! I always thought restaking was just some fancy word for double dipping but seeing the breakdown on native vs liquid makes way more sense. The part about renting out your basement really clicked for me lol. Gonna look into Ether.fi now since i dont wanna run a whole node myself.

- Lukas Scott
- September 30, 2026 AT 21:22 PM
The analogy of the house is charming, yet it fails to capture the profound philosophical shift occurring here. We are witnessing the commodification of trust itself. By allowing capital to secure multiple networks simultaneously, we are not merely increasing yield; we are fundamentally altering the nature of consensus security.
This creates an interconnected web where failure in one peripheral service can cascade into the core layer. It is a move away from siloed security towards a unified, albeit fragile, global security substrate. One must consider whether this efficiency comes at the cost of resilience. The concentration of risk in EigenLayer suggests that we are building a single point of failure for the entire decentralized ecosystem. It is a fascinating, if slightly terrifying, evolution of proof-of-stake mechanics.

- Sandra Speakerworth
- October 1, 2026 AT 20:05 PM
I appreciate the balanced perspective provided here. It is crucial to acknowledge that while the financial incentives are compelling, the technical complexity introduces new vectors for error that many retail investors may underestimate.
Specifically, the section regarding slashing conditions deserves further emphasis. When users delegate their stake to AVSs, they often do so without fully comprehending the specific operational requirements of each service. This lack of understanding can lead to unintended penalties. Furthermore, the reliance on third-party operators adds a layer of custodial risk that contradicts the ethos of self-sovereignty often championed in crypto circles.
It seems prudent for newcomers to start with simple liquid staking before engaging with restaking protocols. The marginal gain in yield may not justify the increased cognitive load and potential for loss until one has thoroughly tested their understanding of the underlying mechanisms. Patience and education remain the best defenses against market volatility and technical mishaps.

- Richard Holle
- October 2, 2026 AT 00:53 AM
Good guide. Keep it simple.

- Amit Sharma
- October 2, 2026 AT 15:04 PM
Another day another protocol trying to solve problems that don't exist by creating ten new ones. The 'internet bond market' is just a buzzword for leverage. You aren't securing anything, you're gambling on liquidity providers not rug pulling. The article glosses over the fact that most AVSs are vaporware right now. $20 billion locked doesn't mean $20 billion utilized. It's mostly idle capital waiting for a narrative. People are farming yields like it's 2021 all over again, ignoring the systemic fragility. If one oracle fails, the whole chain reacts. It's not innovation, it's just financial engineering wrapped in smart contracts. Most people won't understand the slashing conditions until they lose money. Then they'll blame the exchange, not their own ignorance. Typical cycle. Hype first, pain later. Repeat forever.
Post-Comment
Categories
Popular Articles