
Imagine waking up one morning to find that every cryptocurrency transaction you made on an exchange in Dubai or Singapore is now visible to the Indian Income Tax Department. No more hiding behind anonymous wallets or hoping the taxman doesn’t check the blockchain. This isn’t a hypothetical scenario; it’s the reality coming your way by April 2027. The Crypto-Asset Reporting Framework (CARF), developed by the OECD, is set to land in India with full force, fundamentally changing how we report digital assets.
You might be thinking, "Isn't this just another regulation?" But here’s the kicker: India has officially committed to implementing CARF starting April 1, 2027. This move aligns India with over 50 other jurisdictions globally, creating a web of transparency that leaves little room for offshore tax evasion. If you hold crypto outside India, or even if you trade heavily within domestic exchanges, your financial footprint is about to become much clearer to authorities.
The Shift from CRS to CARF
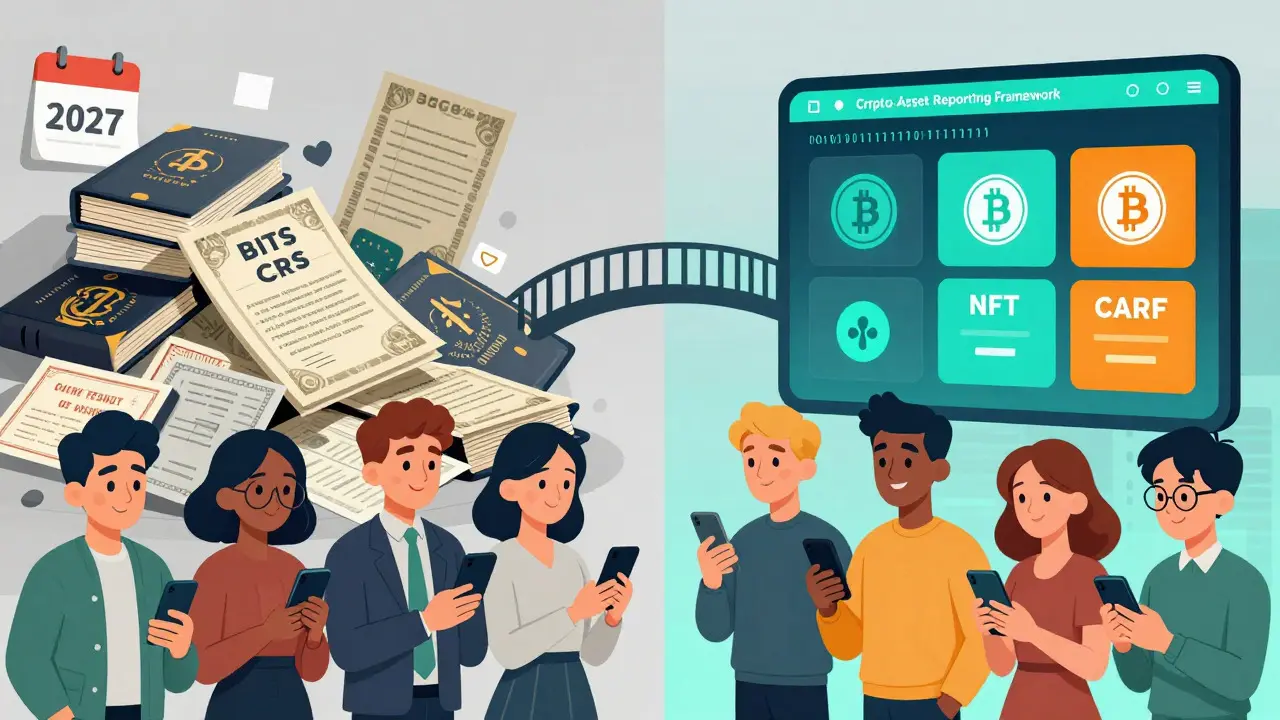
To understand why CARF matters, you need to look at what came before it. Since 2015, India has participated in the Common Reporting Standard (CRS). This system forced banks and traditional financial institutions to share data about account holders with foreign tax authorities. It worked well for bank accounts, mutual funds, and stocks. But crypto? It slipped through the cracks. Traditional banking rules didn’t fit decentralized ledgers and global exchanges that don’t always have a physical branch in New Delhi.
CARF is essentially CRS but built specifically for the digital age. It extends the automatic exchange of tax information to crypto-assets. Think of it as closing the loop. While CRS covered your savings account, CARF covers your Bitcoin holdings on Binance or your Ethereum staking rewards on Coinbase. The goal is simple: ensure that income generated from digital assets is reported and taxed correctly, regardless of where the platform is hosted.
Timeline and Legislative Milestones
When does all this actually hit home? The timeline is tight but clear. India announced its commitment in late 2024, aiming for full implementation by April 1, 2027. However, the groundwork starts earlier. The Finance Bill 2025 introduces Section 285BAA under the Income Tax Act. This section mandates that designated reporting entities-think crypto exchanges and service providers-must collect and report specific user data.
Here is the critical breakdown of dates you should keep in mind:
- April 1, 2026: Section 285BAA takes effect. Exchanges begin collecting detailed data on transactions and holdings.
- January 1, 2026: Data collection standards kick in, following OECD XML guidelines published in October 2024.
- April 1, 2027: Full CARF implementation begins. Automatic exchange of this data with foreign jurisdictions starts.
This gives businesses roughly a year to upgrade their systems. For you, the investor, it means that any offshore activity after early 2026 will likely be captured and shared. Don’t wait until 2027 to start organizing your records.
Who Is Affected?
If you think this only affects whales trading millions in DeFi, think again. The scope is broad. Any individual holding crypto assets through a reporting entity is potentially affected. This includes users of centralized exchanges like WazirX, CoinDCX, or international platforms like Binance and Kraken that serve Indian customers.
But it goes beyond just trading. Staking, lending, and even certain NFT transactions may fall under the radar depending on how they are classified by the reporting entity. The key factor is whether the platform is considered a "Crypto Asset Service Provider" (CASP) under the new rules. Most major exchanges will qualify. Smaller peer-to-peer traders might face different hurdles, but the trend is toward comprehensive coverage.
| Feature | Common Reporting Standard (CRS) | Crypto-Asset Reporting Framework (CARF) |
|---|---|---|
| Target Assets | Bank accounts, securities, insurance products | Cryptocurrencies, stablecoins, CBDCs, tokenized assets |
| Reporting Entities | Banks, custodians, investment funds | Crypto Asset Service Providers (CASPs), exchanges, wallet providers |
| Data Exchange | Annual exchange of balance and income info | Exchange of transaction details, holdings, and identity data |
| Implementation Status | Active since 2015-2017 | Global rollout targeting 2027 |
Compliance Challenges for Users and Businesses
Let’s be real: compliance is messy. For crypto exchanges, the burden is heavy. They need to integrate new software to track KYC (Know Your Customer) data against transaction histories in real-time. The OECD has released XML User Guides to standardize this, but technical integration is no small feat. Expect some smaller platforms to struggle or merge with larger entities that can afford the tech stack.
For you, the user, the main challenge is privacy and complexity. You’ll need to provide more detailed personal information to exchanges. Anonymous trading becomes harder. Also, if you use multiple platforms, reconciling your tax returns will require careful record-keeping. Tools like Koinly or CoinTracker might become essential rather than optional. The fear among many is that increased visibility leads to aggressive taxation, though proponents argue it brings legitimacy to the sector.
Why India Joined the Global Coalition
India didn’t join CARF in isolation. During its G20 Presidency, the New Delhi Leaders’ Declaration unanimously endorsed the framework. This was a strategic move. With over 100 million crypto users, India represents one of the largest markets globally. Without India’s participation, CARF would lack significant weight. By joining, India signals to the world that it intends to regulate digital assets seriously, moving away from the uncertainty of the past few years.
This alignment also helps combat tax evasion. Previously, Indians could park wealth in offshore crypto accounts with relative ease. Now, that money is visible. The government aims to capture revenue from capital gains and mining rewards that previously went unreported. It’s a shift from reactive enforcement to proactive data gathering.
What Should You Do Now?
Don’t panic, but do prepare. Here is a practical checklist to get ahead of the curve:
- Audit Your Holdings: List every exchange and wallet where you hold crypto. Note down the location of the exchange’s headquarters.
- Update KYC Documents: Ensure your ID proofs and address documents are current and match across all platforms.
- Track Transactions: Start keeping detailed logs of trades, especially those involving cross-border transfers. Export CSV files regularly.
- Consult a Tax Advisor: Find a professional who understands both Indian tax laws and crypto specifics. Generic advice won’t cut it here.
The transition period between 2026 and 2027 is your window to clean up your portfolio. Messy records now mean headaches later when the data hits the tax department automatically.
Frequently Asked Questions
Will CARF apply to my hardware wallet?
Generally, self-custodied hardware wallets are not directly reported by a third party because there is no service provider acting as an intermediary. However, if you transfer funds from a centralized exchange to your hardware wallet, the initial withdrawal transaction will be recorded by the exchange. The focus remains on transactions involving Crypto Asset Service Providers.
Does CARF mean higher taxes for me?
Not necessarily. CARF is a reporting framework, not a tax rate change. It ensures that existing tax laws are applied correctly. If you have been paying your 30% tax and 1% TDS correctly, CARF shouldn’t increase your bill. It mainly targets those who have underreported income or held assets offshore without declaring them.
What happens if I fail to report my crypto assets?
Non-compliance can lead to penalties under the Income Tax Act. Once the data is exchanged automatically, discrepancies between your filed returns and the received data will trigger audits. Penalties can include fines and interest on unpaid taxes. In severe cases of willful concealment, stricter legal actions may follow.
Are DeFi transactions covered by CARF?
This is complex. Purely decentralized transactions without a central intermediary are harder to report. However, if you interact with DeFi protocols through a centralized interface or aggregator that qualifies as a CASP, those interactions may be reported. The OECD continues to refine definitions to cover emerging DeFi structures.
Can I still use offshore exchanges?
Yes, but they must comply with CARF if they serve Indian residents. Major global exchanges are already upgrading their systems to meet these standards. Using non-compliant offshore exchanges might result in blocked withdrawals or additional scrutiny from Indian tax authorities.
Comments (9)

- Martha Packard
- August 30, 2026 AT 16:52 PM
Another layer of surveillance dressed up as 'transparency.' We all know this isn't about fairness, it's about control and squeezing every last rupee from the middle class while the elites keep their assets in jurisdictions that conveniently don't play ball with OECD whims. The government loves to talk about 'legitimizing' crypto when they really just want a bigger slice of the pie without offering any actual utility or infrastructure improvements for the common user.

- Jarnail Singh
- September 1, 2026 AT 16:48 PM
This is exactly what India needs to mature as a financial hub 🙌🏽
We have been lagging behind Singapore and Dubai for too long because of our hesitation and regulatory ambiguity which scared away serious institutional investors who wanted clear rules not vague warnings from RBI officials who probably still think Bitcoin is magic internet money. By joining CARF we are finally signaling to the world that we are open for business and that our tax system is robust enough to handle complex digital asset flows which will inevitably bring more foreign direct investment into our tech sector.
The fact that we had over 100 million users before even having proper reporting standards shows the sheer appetite of the Indian public for innovation and if we can streamline this process we might actually see domestic exchanges like CoinDCX compete on a global stage instead of being relegated to local retail trading platforms which is honestly a waste of potential talent and capital liquidity.
I am proud that our G20 presidency led to this declaration because it proves that we are not just passive participants in the global economy but active shapers of future financial norms and regulations which is a testament to the intellectual rigor and diplomatic skill of our policymakers who understand that regulation must evolve alongside technology rather than trying to stifle it with outdated banking laws from the 1990s era.
Of course there will be challenges with compliance costs for smaller entities but those who cannot adapt deserve to be left behind in the dustbin of history because progress waits for no one and neither should our tax department which has been playing catch-up for far too long 😎

- Aaliyah Simpson
- September 2, 2026 AT 17:05 PM
Great, now Big Brother knows exactly when I bought my shitcoins so he can come knocking at my door asking for his cut before I've even realized I made a profit. They say it's for transparency but let's be real, it's for tracking everyone's movements and building a complete profile of your life based on your wallet address. I bet half these regulators don't even know how a blockchain works but they sure know how to fine you for existing incorrectly.

- Paul Needham
- September 2, 2026 AT 22:29 PM
Oh wow, another government initiative to make things harder for people who actually try to manage their own finances instead of trusting banks to lose their money. You're acting like this is some conspiracy when it's literally just standardizing data formats so computers can talk to each other without needing a human interpreter who charges by the hour. If you can't handle filling out a form or letting an exchange upload a CSV file, maybe you shouldn't be playing in the sandbox with adults who pay taxes properly.

- Ashwini Chaskar
- September 4, 2026 AT 02:27 AM
it feels so unfair really that we have to jump through hoops while the big whales just move their stuff around and stay invisible anyway its always the little guy getting squeezed i feel like crying just thinking about all the paperwork coming our way and nobody cares about our privacy anymore its all gone gone gone

- Sam Ariafar
- September 4, 2026 AT 06:17 AM
Privacy is a privilege, not a right, especially when you are participating in a system that relies on trust and verification. Those who hide their assets often do so because they are hiding income that was never taxed in the first place. It is only moral to ensure that everyone contributes their fair share to the society that provides the infrastructure allowing them to trade in the first place.

- Jillian Pye
- September 5, 2026 AT 19:09 PM
I appreciate the clarity on the timeline. :)
It seems wise to start organizing records now rather than waiting for the panic of 2027. There is something comforting about knowing the boundaries of the law, even if they feel restrictive at times. It allows us to plan our lives with a bit more certainty regarding our obligations.

- Linda Jevne
- September 6, 2026 AT 04:13 AM
The shift from CRS to CARF represents a fascinating evolution in how nations conceptualize value itself. We are moving from tangible ledgers to ethereal ones, yet the state insists on pinning down these ghosts with bureaucratic pins. It is almost poetic, isn't it? The attempt to impose order on chaos through XML schemas and standardized codes. One wonders if this will lead to a homogenization of global finance, stripping away the unique cultural nuances of different markets in favor of a sterile, universal language of compliance. Yet, within this structure, there lies the potential for true equity, where the anonymous whale and the daily trader stand under the same spotlight, illuminated by the harsh light of data.

- Melanie Armijo
- September 7, 2026 AT 19:17 PM
Hey everyone! Just wanted to add that I think the key here is preparation. It’s totally manageable once you get the hang of it! Think of it like spring cleaning for your portfolio. Once it’s done, you’ll feel so much lighter and ready for whatever comes next. Good luck with the audits! ✨